

On This Day in Business: September 25, 2008
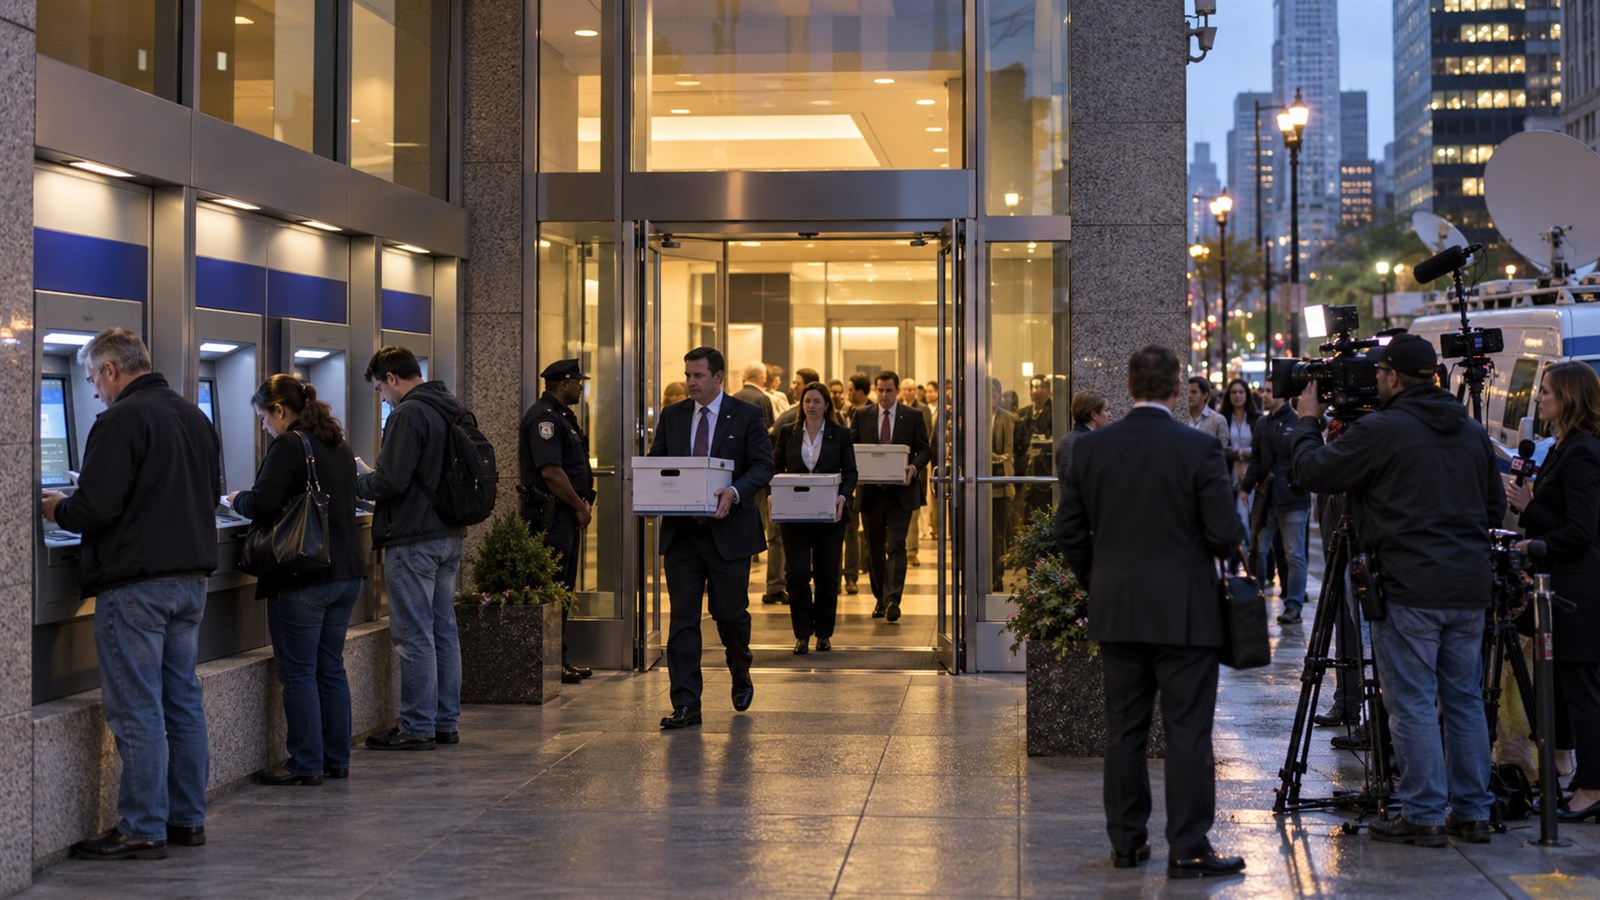
Regulators closed Washington Mutual Bank on September 25, 2008, and appointed the Federal Deposit Insurance Corporation as receiver. With about $307 billion in assets, WaMu became the largest bank failure in FDIC history. JPMorgan Chase acquired the bank's operations, deposits, and most assets in a transaction that imposed no loss on the Deposit Insurance Fund. Customers retained access to their accounts and checks continued to clear. The smooth transfer of ordinary banking services contrasted sharply with the scale of the institution's collapse.
WaMu had expanded aggressively in residential mortgages, including option adjustable-rate loans and other products vulnerable to falling home prices and borrower stress. Weak underwriting and risk controls left the bank exposed as the housing market deteriorated. After several major financial failures in September 2008, depositors withdrew significant funds and creditors grew more cautious. A bank can hold long-term loans that may eventually repay while still failing if enough short-term funding leaves at once. The accelerating outflow gave supervisors little time to wait for a gradual recovery.
Deposit insurance and resolution planning prevented a disorderly retail run from inflicting losses on insured customers. The FDIC's role was not to preserve shareholders or management; it was to maintain confidence in deposits and transfer essential operations. JPMorgan's purchase created immediate continuity across branches, ATMs, direct deposits, loans, and payment systems. Equity investors and some creditors did not receive the same protection, preserving the distinction between insured banking services and risk-bearing capital.
WaMu's failure became a major case study in supervision, governance, mortgage incentives, liquidity, and the speed of digital-era withdrawals. It showed that rapid asset growth can conceal weakening loan quality and that a familiar consumer brand does not eliminate balance-sheet risk. The September 25 resolution also demonstrated why banking requires specialized failure procedures: closing a large institution without interrupting millions of customer relationships is an operational project as much as a legal one. The broader lesson is that stability depends on both prevention and credible cleanup. Capital, underwriting, and liquidity controls reduce the chance of failure, while deposit insurance and a prepared receiver limit the damage when those controls prove insufficient. Speed was essential because uncertainty can itself trigger withdrawals. Announcing a buyer and maintaining service before the next business day prevented operational confusion from becoming additional panic. A prepared resolution plan therefore creates value not only through recovery but through the confidence produced by a clear transition. Preparation preserved trust.
Regulators closed Washington Mutual Bank on September 25, 2008.
Its $307 billion in assets made it the largest failure in FDIC history.
Mortgage losses, weak underwriting, and rapid funding withdrawals undermined the bank.
The FDIC transferred deposits and most assets to JPMorgan Chase without cost to its insurance fund.
Customers kept access to branches, checks, direct deposits, ATMs, and contractual loan terms.
The resolution showed the value of deposit insurance and specialized procedures for closing a large bank.
Explore more of "On This Day ..."
Discover more events from the same date across news, politics, technology, sports, and other fields. Each link highlights significant moments that shaped history on different fronts.