

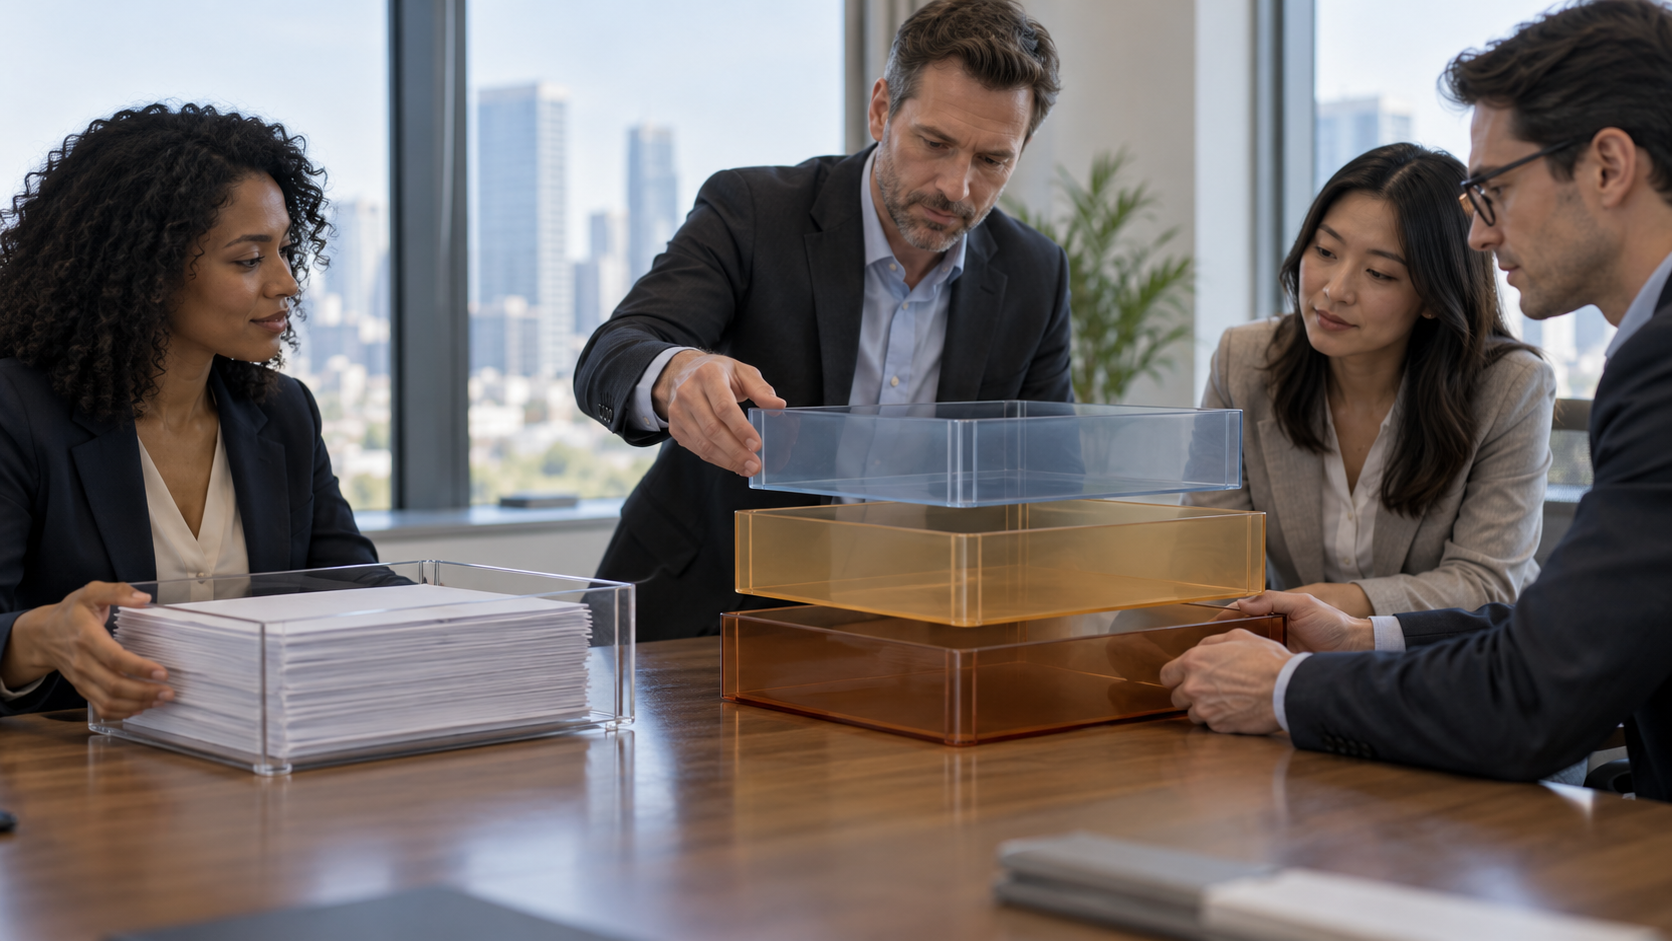
Structured-Finance Tranches Explainer
A tranche is one class of securities issued against a shared asset pool. Transaction documents allocate interest, principal, fees, and losses among classes in a defined waterfall. Senior tranches are paid before junior tranches, while the most subordinate layer absorbs initial losses.
Subordination creates credit enhancement. A tranche’s attachment point indicates how much pool loss occurs before it begins losing principal, and its detachment point marks when it is fully exhausted. Thickness, reserves, excess spread, and triggers also influence protection.
Tranches can differ in coupon, maturity, rating, prepayment exposure, and sensitivity to changing collateral performance. A senior class can receive a high rating even when some underlying assets are risky because junior capital absorbs losses first, but that protection depends on model assumptions and actual correlation.
Waterfalls can redirect cash when performance tests fail, helping senior holders while cutting off junior payments. Complexity creates model, legal, operational, and liquidity risk. Investors should examine the pool, priority rules, trigger definitions, manager or servicer, scenario losses, and how cash timing changes under stress.
Each tranche has its own priority, coupon, and risk profile.
The waterfall governs payments.
Subordination absorbs early losses before higher classes are hit.
Protection is finite.
Correlation, triggers, and cash-flow timing can change outcomes.
A rated tranche is not a guarantee.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.