

Asset Impairment Explainer
Asset impairment occurs when an asset’s carrying amount is no longer recoverable or exceeds the amount supported under the applicable accounting standard. It can affect equipment, buildings, intangible assets, goodwill, and other long-lived resources. The exact test differs by asset type and reporting framework, but the purpose is to prevent assets from remaining recorded at unsupported amounts.
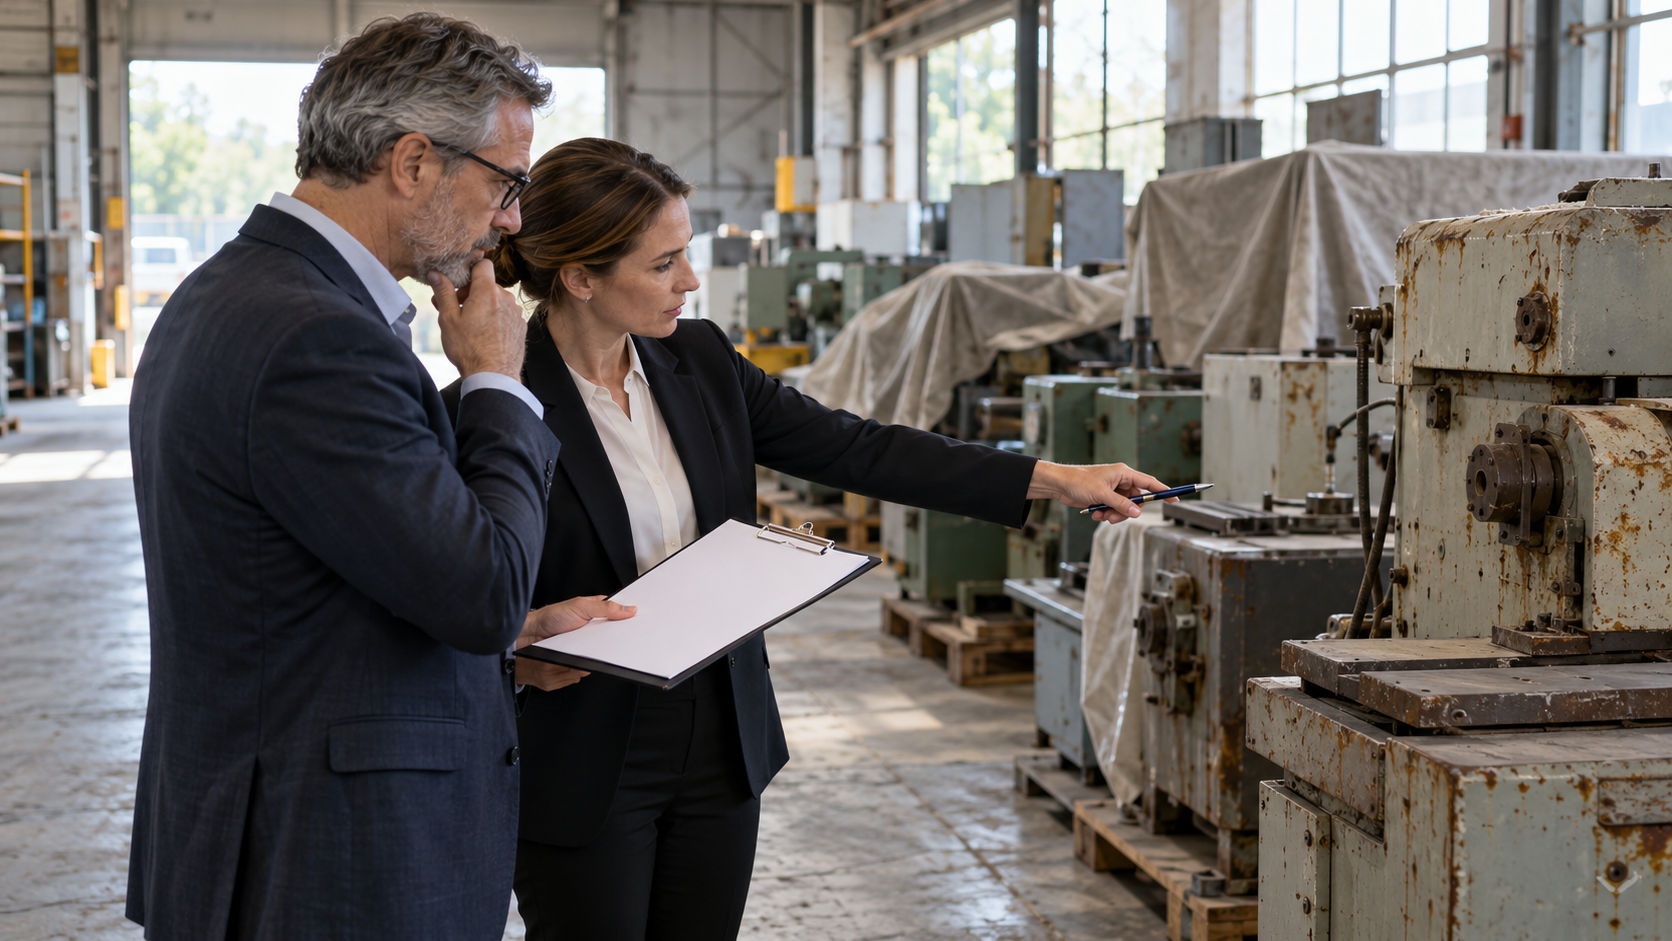
Warning signs can include physical damage, obsolescence, adverse regulation, lost customers, lower market values, weak operating results, a plan to dispose of an asset, or a significant decline in expected cash flows. Some assets are tested when indicators arise, while goodwill and indefinite-lived intangibles may have additional periodic requirements.
Testing often requires grouping assets at the level where cash flows can be evaluated and comparing carrying value with a recoverability or fair-value measure. Forecasts, discount rates, useful lives, market evidence, and allocation methods may all matter. An impairment loss reduces the asset and current-period earnings, but it does not itself represent a new cash payment.
Impairment differs from regular depreciation or amortization, which allocates cost systematically over an expected useful life. Because tests involve judgment, teams should document indicators, data sources, scenarios, approvals, and sensitivity. Current standards and qualified valuation or accounting advice are important for material conclusions.
Damage, obsolescence, weaker cash flows, lost customers, or adverse market changes can trigger review.
The required timing depends on the asset and reporting framework.
Forecasts, discount rates, market evidence, useful lives, and asset groupings can affect the result.
Document sources and test the conclusion under reasonable alternative assumptions.
Depreciation allocates cost over time, while impairment addresses an unsupported carrying amount.
The loss reduces accounting earnings without creating a new cash outflow at the test date.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.