

American vs. European Options Explainer
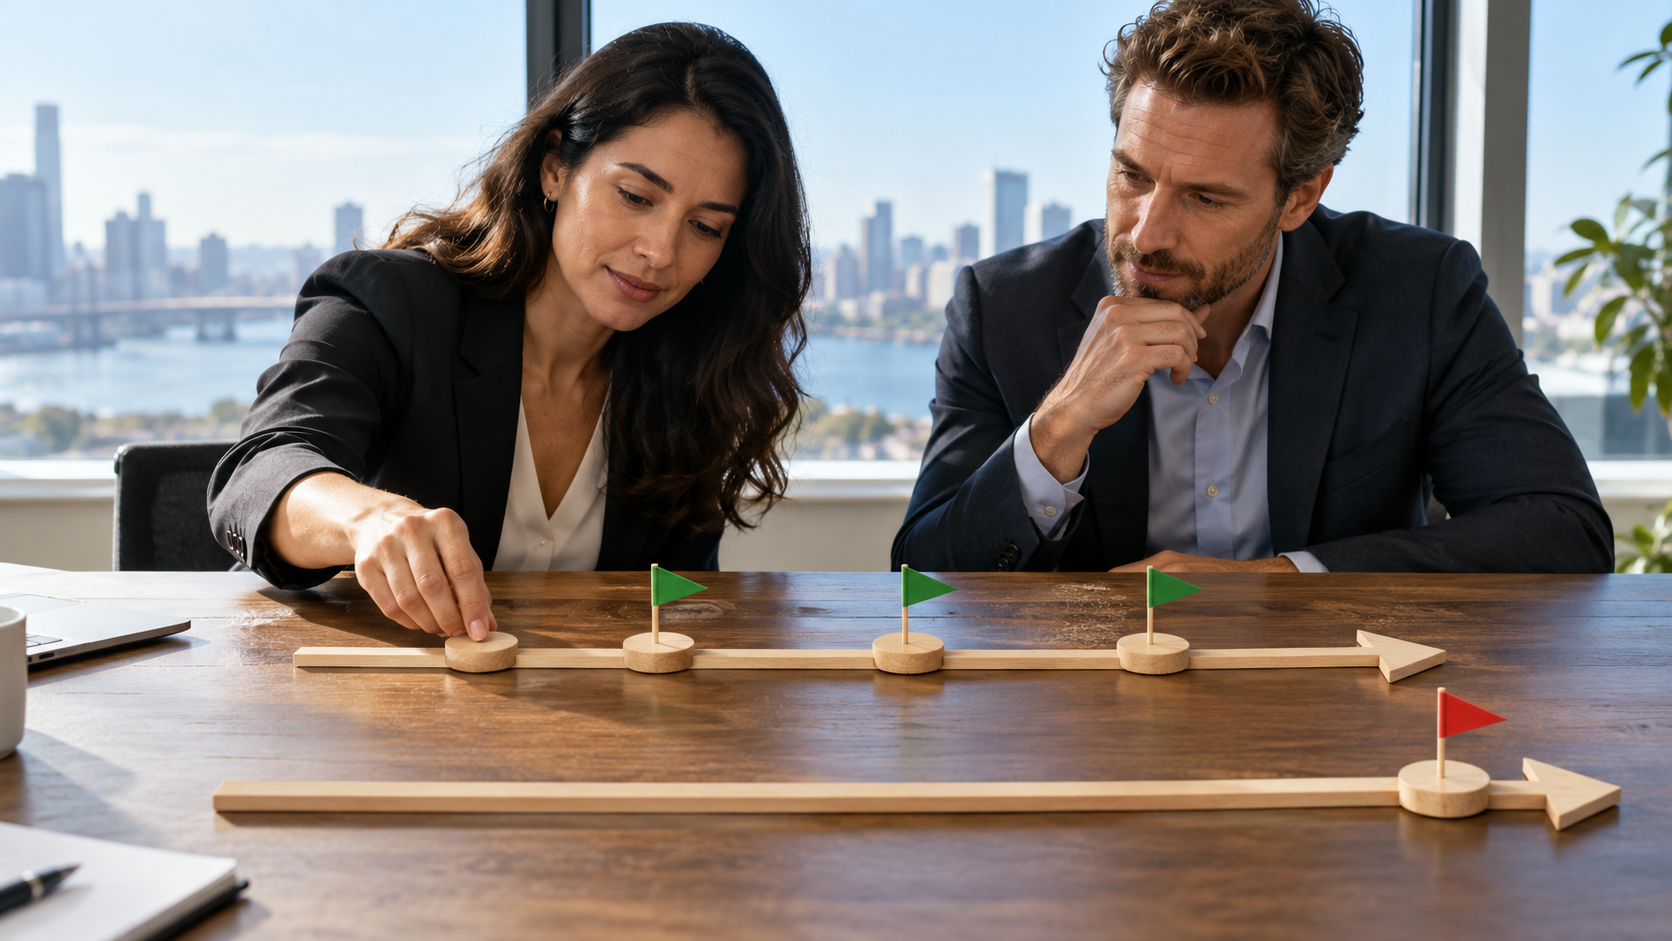
American and European are exercise-style labels, not descriptions of where an option trades. An American-style holder can generally exercise on any permitted business day through expiration, while a European-style holder can exercise only at the contract’s specified end point.
Many U.S. equity options are American style, and many broad-based index options are European style, but investors must confirm each product. Exercise style is separate from physical or cash settlement, trading hours, the settlement calculation, and the final trading date.
Early exercise can matter around dividends, financing costs, borrow constraints, or deep intrinsic value. The possibility also creates early-assignment risk for American-style writers. European-style contracts remove that timing uncertainty before expiration but can still move sharply in price.
Exercise flexibility can influence theoretical value, yet it does not make one style universally better. Product terms, liquidity, tax treatment, settlement exposure, and the exact reference value often dominate practical results. Read the contract specification instead of inferring rules from the name.
American style generally allows early exercise.
European style restricts exercise to the specified endpoint.
Either style can trade in many markets.
Verify the actual contract, not the label’s cultural meaning.
Cash versus physical delivery and final pricing require their own review.
Exercise style alone does not reveal the payoff process.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.