

Bond Convexity Explainer
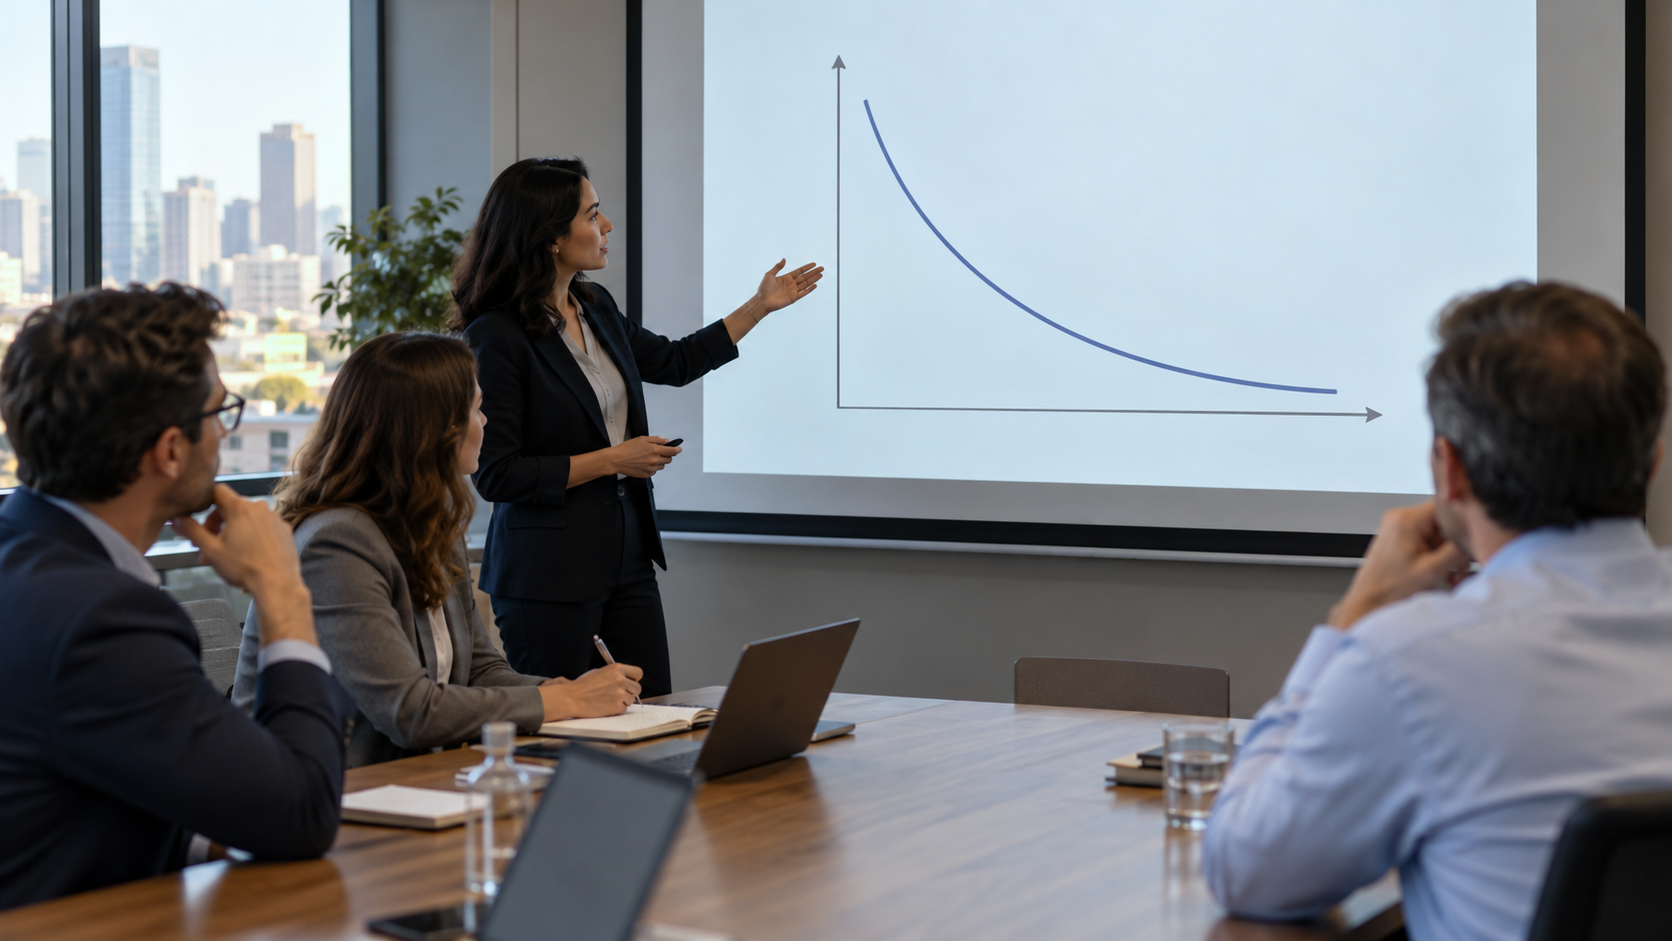
Bond convexity measures the curvature of the price-yield relationship. Duration gives a useful first-order estimate of how price may change for a small yield move, while convexity adjusts that estimate because bond prices do not move along a straight line as yields change.
For a conventional option-free bond, price usually rises more when yields fall than it falls for an equal yield increase. This positive convexity can improve outcomes relative to a duration-only estimate. Longer maturities and different cash-flow patterns can increase convexity, though coupon and yield levels also matter.
Embedded options can reverse the pattern. A callable bond may show negative convexity when falling rates make redemption more likely, limiting price gains. Mortgage-backed securities can also lose expected duration as homeowners refinance, while rising rates may extend cash flows and increase sensitivity.
Portfolio managers use convexity with duration to compare bonds, hedge rate exposure, and estimate scenario results. The measures depend on models, yield changes, and cash-flow assumptions. They do not capture every credit, liquidity, spread, or option risk, especially when large market moves change borrower or issuer behavior.
Duration approximates a straight-line price response.
Convexity accounts for curvature.
Price gains from falling yields can exceed losses from an equal rise.
Cash-flow structure shapes the effect.
Calls and mortgage prepayments can create negative convexity.
Model assumptions become crucial.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.