

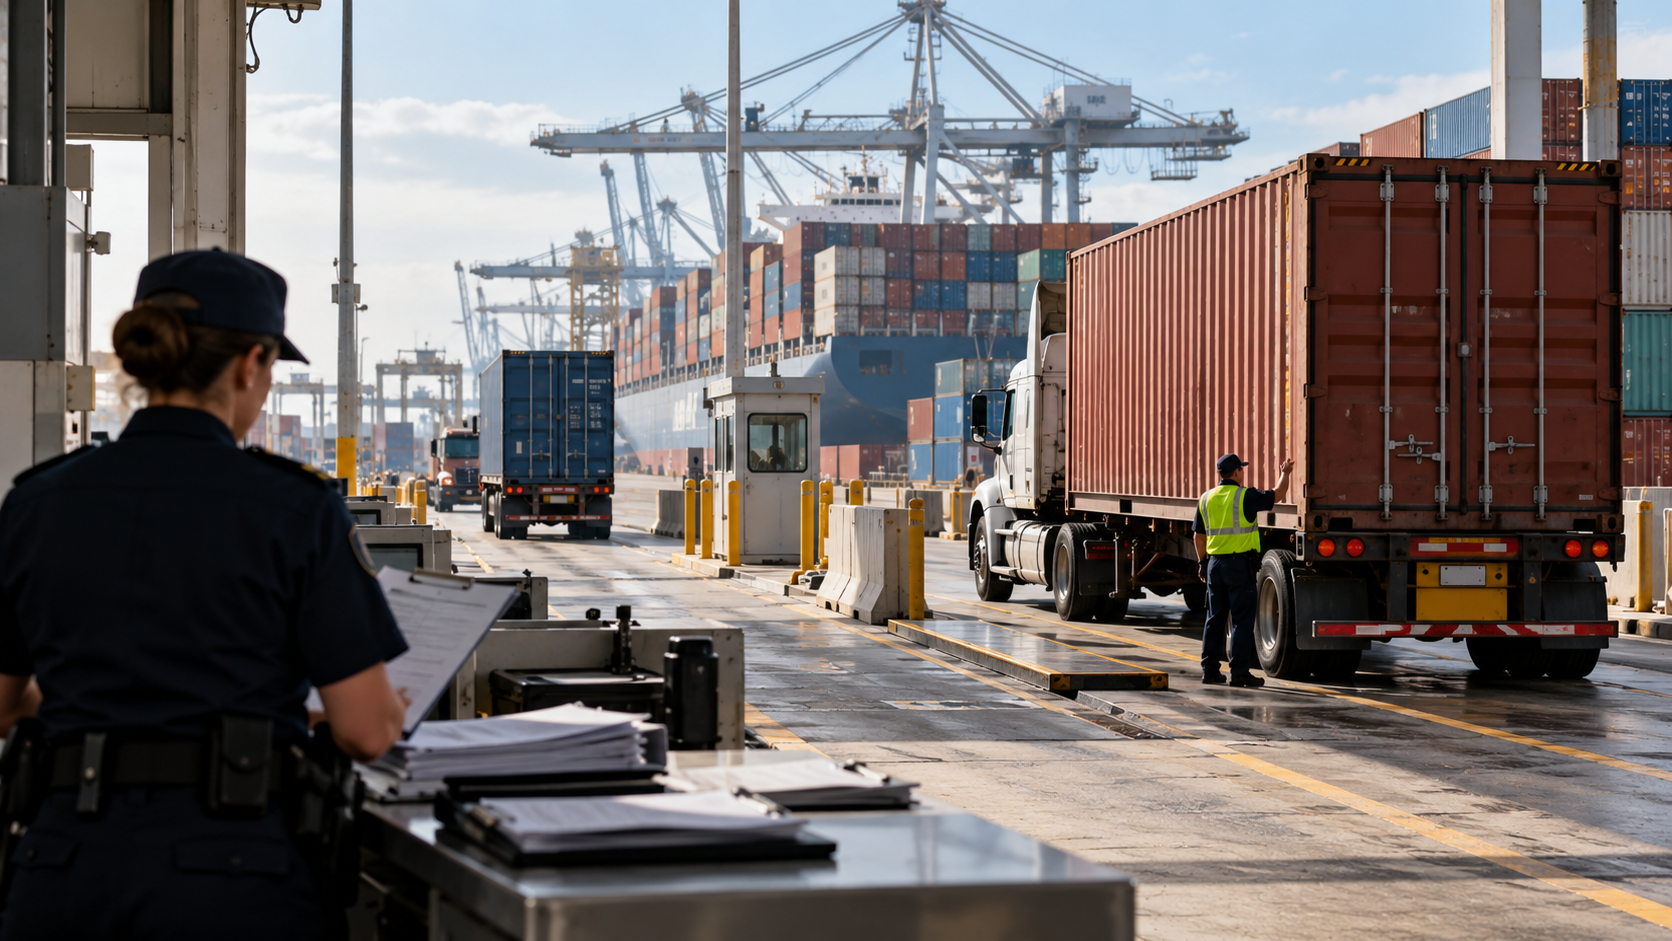
Import-Export Clause Explainer
Import-Export Clause is Article I’s restriction on state imposts or duties on imports and exports without congressional consent, apart from charges absolutely necessary to execute inspection laws. It matters because it protects national control over foreign commerce and prevents individual states from turning international trade into a competing source of customs revenue. The concept belongs to a constitutional system that divides authority, creates procedures, and asks public institutions to justify how they use power.
The foundation begins with the Framers’ experience under the Articles of Confederation, when port states could burden goods destined for neighboring states and weaken a unified national trade policy. The operative legal framework is this: Article I, Section 10 directs net revenue from permitted inspection charges to the United States Treasury and makes such laws subject to congressional revision and control. Read together, those sources explain both the provision’s democratic purpose and the institutional setting in which officials, courts, and the public evaluate it.
In practice, courts look at the character and purpose of a state charge, including whether it functions as a tax on goods because of their import or export status rather than as a generally applicable levy. A useful illustration is that a nondiscriminatory property tax after imported goods lose their distinctive import character may be valid, while a special duty imposed simply because goods arrived from abroad raises the clause directly. Real disputes rarely turn on a label alone; they require attention to the responsible institution, the legal trigger, the available record, and the remedy or consequence that follows.
The most important boundary is that the clause is not a blanket exemption from every state tax touching international commerce, and modern analysis distinguishes prohibited imposts from ordinary taxes and legitimate inspection fees. The continuing policy and legal debate is that the recurring question is how to preserve federal uniformity without unnecessarily disabling states from taxing property and services within their borders. Understanding both the governing rule and its limits helps readers separate ordinary disagreement from a genuine constitutional conflict.
the Framers’ experience under the Articles of Confederation, when port states could burden goods destined for neighboring states and weaken a unified national trade policy. Article I, Section 10 directs net revenue from permitted inspection charges to the United States Treasury and makes such laws subject to congressional revision and control.
This background matters because constitutional rules usually grow from a concrete governance problem rather than abstract theory alone. The text must be read with surrounding structure, historical practice, implementing statutes, and the facts of a particular dispute. Examining those sources together prevents a memorable label from replacing the legal inquiry the provision actually requires.
courts look at the character and purpose of a state charge, including whether it functions as a tax on goods because of their import or export status rather than as a generally applicable levy. a nondiscriminatory property tax after imported goods lose their distinctive import character may be valid, while a special duty imposed simply because goods arrived from abroad raises the clause directly.
Each step creates a record that may be reviewed by other officials, courts, auditors, voters, or the public as governing law permits. Timing and institutional authority can matter as much as the outcome, so sound analysis begins with the exact source of the challenged action. Concrete records help distinguish a lawful use of power from an attractive description unsupported by the relevant facts or procedures.
the clause is not a blanket exemption from every state tax touching international commerce, and modern analysis distinguishes prohibited imposts from ordinary taxes and legitimate inspection fees. the recurring question is how to preserve federal uniformity without unnecessarily disabling states from taxing property and services within their borders.
Those boundaries protect competing constitutional values and keep useful powers from becoming unlimited. Enforcement may depend on litigation, congressional oversight, executive review, elections, or several mechanisms working together, with reasonable observers assigning different weight to accountability, expertise, speed, uniformity, and local autonomy. Durable governance therefore combines a clear rule with transparent reasons, meaningful review, and remedies suited to the institution involved.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.