

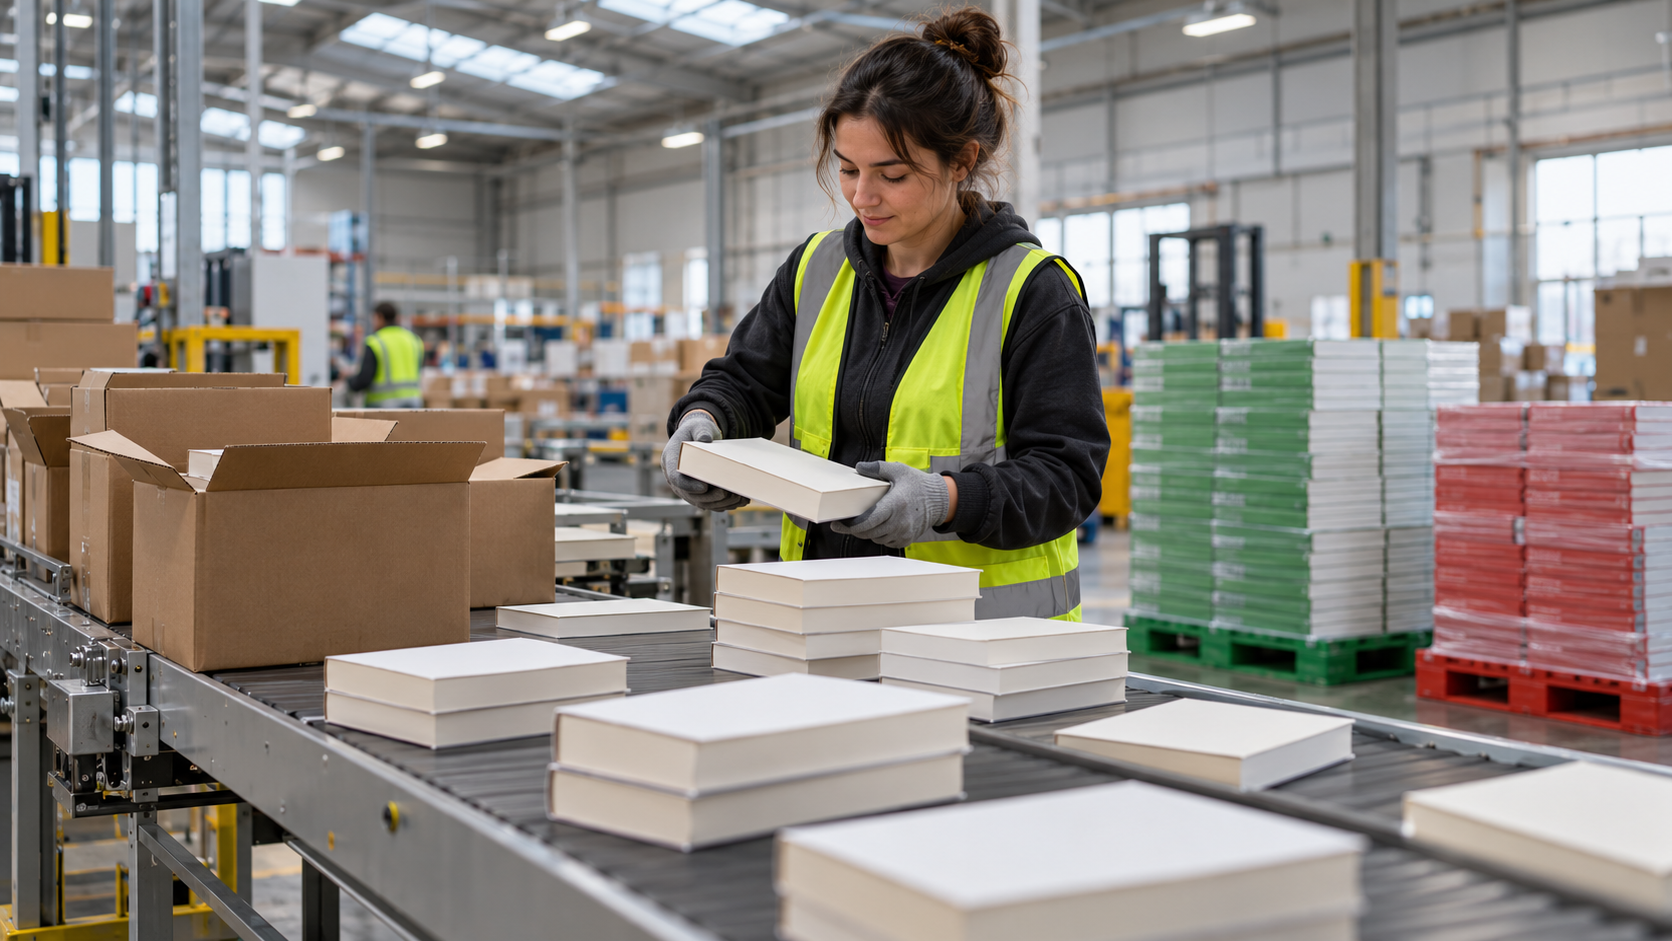
Book Sales Returns Explainer
In much of the trade book business, eligible retailers can return unsold copies to a wholesaler or publisher for credit under agreed terms. This returnability reduces the retailer's risk of stocking uncertain titles and helps publishers place books broadly. It also means a shipment into stores is not necessarily a final sale to a reader. Gross units shipped, net sales after returns, and point-of-sale purchases describe different stages.
The system grew from the need to encourage shelf space for many new titles, but it transfers demand risk upstream. Publishers print and ship based on forecasts, publicity, orders, season, comparable titles, and retailer expectations. If demand is lower, copies flow back. Some can be restocked; others are damaged, stripped, remaindered, recycled, or destroyed, depending on format and policy. Each path has cost and environmental consequences.
Returns affect accounting. Contracts often calculate author royalties on net copies sold or revenue received, subject to the agreement, and publishers may hold a reserve against future returns before releasing some royalties. A large initial shipment can therefore look encouraging without representing durable sales. Later returns can reduce the net position. Royalty statements need to be read using the contract's definitions, periods, formats, discounts, and reserve provisions.
Retailers and publishers try to improve the forecast with preorder data, comparable sales, local knowledge, replenishment systems, and shorter print cycles. Print-on-demand and digital editions reduce some inventory exposure but do not eliminate every commercial risk. Nonreturnable discounts shift risk toward the buyer and may suit specialized channels, direct sales, or proven demand. There is no single best policy for every book, store, or market. Returns reveal a structural tension in publishing. Wide availability increases the chance that readers discover a title, while excess placement creates freight, labor, cash-flow, and waste. Evaluating a release therefore requires more than the number of copies printed or shipped. Sell-through, net sales, timing, channel, condition, and return rate together show how much inventory found lasting demand and how much completed a costly round trip. A practical way to read or discuss Book Sales Returns is to begin with the basic definition and then identify the choices made in a particular example. Returnability lets eligible booksellers send unsold copies back for credit under the supplier's agreed terms. Next, ask who sets the relevant rules, who performs the work, and which results follow from creative judgment, law, contracts, technology, budget, or production limits. Similar-looking examples can operate differently because their audience, market, format, timing, and agreements are different. Royalties and reserves follow the specific publishing contract, accounting period, format, discount, and sales definition. It also helps to distinguish a formal industry category from an informal critical label or one organization's current practice. That separation keeps a memorable anecdote from becoming a false universal rule. Dates and territories matter: tools, distribution systems, audience behavior, and standard agreements change, while older examples can preserve assumptions that no longer apply everywhere. Because the concept sits inside a larger workflow, examine what comes before and after it, which records move between stages, and where responsibility changes hands. This broader view prevents one visible task from being mistaken for the entire system. When a claim sounds absolute, compare it with a second kind of source and look for the conditions under which the claim is true. Then trace the process from the visible result back through the less visible decisions, handoffs, and quality checks that produced it. Sell-through and net sales provide more context than a large initial shipment viewed in isolation. Finally, compare the example with a contrasting case and note which part of the definition still holds. This method keeps the explanation grounded, highlights the people and systems behind the outcome, and leaves room for reasonable disagreement about hybrid or borderline cases.
Returnability lets eligible booksellers send unsold copies back for credit under the supplier's agreed terms.
Copies shipped into a channel are not the same measure as consumer purchases or final net sales after returns.
Returned books may be restocked, sold through other channels, remaindered, recycled, or destroyed depending on condition.
Royalties and reserves follow the specific publishing contract, accounting period, format, discount, and sales definition.
Preorders, replenishment, smaller print runs, print-on-demand, and nonreturnable terms redistribute different risks.
Sell-through and net sales provide more context than a large initial shipment viewed in isolation.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.