Business - This Explainer

Letters of Credit

A letter of credit is a bank’s commitment to pay a beneficiary when specified documents comply with stated terms. In international trade, an importer asks its bank to issue the letter for an exporter. The arrangement substitutes the bank’s payment promise for reliance solely on the buyer, helping parties that lack a long operating history together. After shipment, the exporter presents required documents, which may include invoices, transport records, insurance certificates, or inspection evidence. Banks examine documents rather than the physical goods. A discrepancy can delay payment or require the buyer to waive the defect, even when the underlying shipment is commercially acceptable.
Business - This Explainer

Trade Credit

Trade credit arises when a supplier delivers goods or services before the customer pays. Terms such as net 30 give the buyer time to generate sales or cash before settlement. For many companies, accounts payable is a major source of short-term operating finance and accounts receivable is a major use of supplier capital. The supplier sets credit limits, payment dates, discounts, late charges, and collection procedures after assessing the buyer. An early-payment term such as 2/10, net 30 offers a discount for prompt settlement. Declining that discount can imply a high annualized financing cost even though no explicit interest rate appears.

Business - This Explainer

Payment Netting

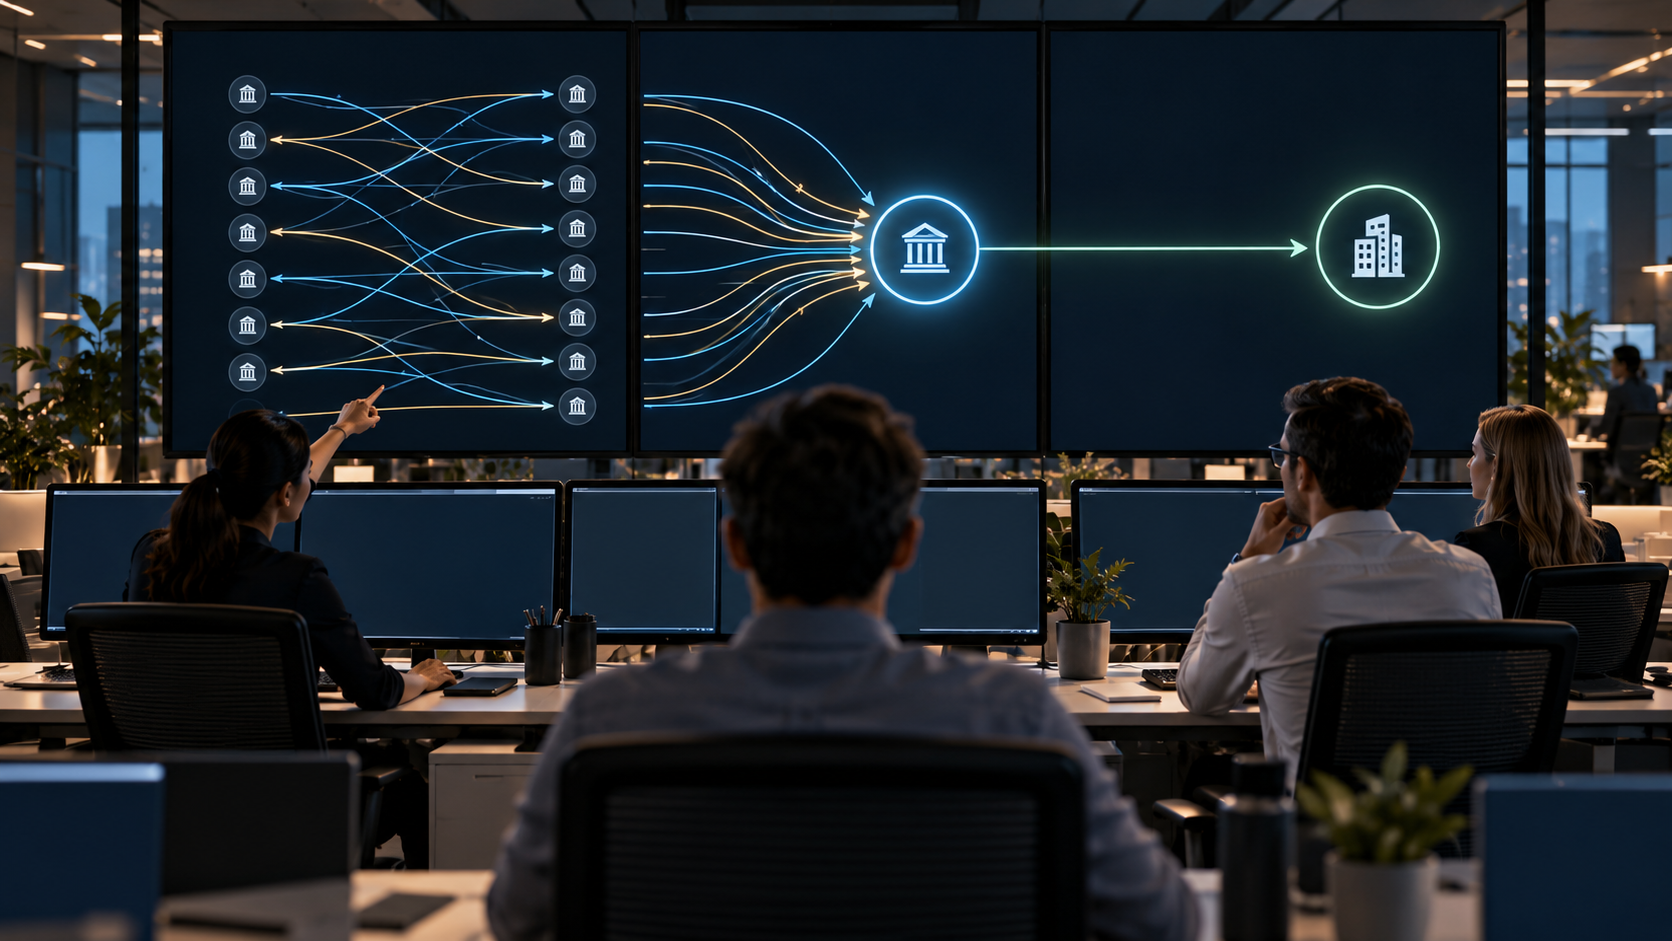
Payment netting offsets obligations between parties so only the remaining balance is transferred. If two companies owe each other money in the same period, bilateral netting can replace two gross payments with one net payment. Multilateral systems extend the idea across many participants and calculate each member’s overall amount due or receivable. Netting can occur by payment, close-out, novation, or contractual setoff, and those forms have different legal effects. Clearing arrangements establish cutoffs, eligible transactions, valuation rules, currencies, collateral, and settlement procedures. Enforceability becomes especially important if a participant defaults or enters insolvency.

Business - This Explainer

Counterparty Risk

Counterparty risk is the possibility that the other side of a financial or commercial contract will fail to perform. The exposure appears in loans, derivatives, securities trades, supply agreements, insurance, and ordinary receivables. Its size depends not only on today’s amount owed but also on how the contract’s value can change before completion. For a derivative, a default may force the surviving party to replace a favorable contract at current market prices. Netting agreements and collateral can reduce exposure, while central clearing can substitute a clearinghouse for bilateral counterparties. Credit limits, guarantees, margin, and termination rights also shape the loss path.

Business - This Explainer

Settlement Risk

Settlement risk is the danger that one party delivers cash or an asset while the other side fails to complete its obligation. It can arise even after a trade is agreed and priced correctly. Time zones, payment cutoffs, manual errors, bank failures, and operational disruptions can leave one leg final while the other remains uncertain. Principal risk is most severe when the full value delivered cannot be recovered. Replacement-cost risk arises when a failed trade must be re-entered at a worse price. Liquidity risk appears when expected receipts do not arrive, forcing a participant to fund another obligation on short notice even if the original counterparty eventually pays.

Business - This Explainer

Clearinghouses

A financial clearinghouse stands between market participants to manage obligations after trades are made and before final settlement. In centrally cleared markets, the clearinghouse becomes buyer to every seller and seller to every buyer through novation or an equivalent legal process. That structure standardizes risk management and reduces a web of bilateral exposures. Members post initial margin for potential future exposure and variation margin as prices change. Default funds, capital, assessments, position limits, and member standards create additional protection. The clearinghouse nets eligible trades and establishes procedures for valuing portfolios, handling collateral, and closing a failed member’s positions.

Business - This Explainer

Custody Services

Custody services safeguard financial assets and administer the records and cash flows associated with ownership. A custodian may hold securities directly, through a central depository, or through subcustodians in other markets. Clients include investment funds, pensions, corporations, banks, advisers, and individuals with complex portfolios. Core tasks include trade settlement, income collection, corporate-action processing, tax documentation, cash management, position reporting, proxy materials, and asset servicing. Fund custodians may also perform duties required by regulation or contract. Ownership records, client instructions, and reconciliation across market infrastructures must remain accurate.

Business - This Explainer

Prime Brokerage

Prime brokerage is a bundle of services that large broker-dealers provide mainly to hedge funds and other active institutional investors. Services can include trade clearing and settlement, custody, securities lending, margin financing, cash management, consolidated reporting, capital introductions, and operational support across multiple executing brokers. A client may place trades with several dealers but route them to a prime broker for financing and centralized records. The prime broker sets margin requirements, values collateral, monitors concentration, and may rehypothecate eligible assets under contract and law. Documentation defines close-out, liquidation, and asset-use rights.

Business - This Explainer

Collateral Haircuts

A collateral haircut is the percentage by which a lender or clearing system reduces an asset’s market value when calculating borrowing capacity. If securities worth one million dollars receive a 10 percent haircut, they support only nine hundred thousand dollars of exposure. The buffer protects against price declines and sale costs after a default. Haircuts vary with volatility, liquidity, maturity, credit quality, currency, concentration, and how quickly the asset could be sold. Additional adjustments may apply when collateral and exposure are closely related or denominated differently. Systems recalculate values and require more collateral when prices fall or risk settings change.

Business - This Explainer

Fair Value Hierarchy

The fair value hierarchy groups valuation inputs by how observable they are in the market. Level 1 uses quoted prices for identical assets or liabilities in active markets. Level 2 relies on other observable inputs, such as comparable prices or yield curves. Level 3 uses significant unobservable inputs developed through models and assumptions. The hierarchy ranks inputs, not the quality or risk of the asset itself. A holding is classified according to the lowest-level input that is significant to the entire measurement. Transfers between levels can occur when market activity, pricing sources, or the significance of assumptions changes.

Business - This Explainer

Impairment Charges

An impairment charge recognizes that an asset’s recorded amount is no longer supported by its expected value under the applicable accounting rules. It can apply to goodwill, long-lived assets, investments, loans, receivables, or other balances. The test and measurement method differ by asset type and reporting framework. Triggering events can include declining sales, higher interest rates, lost customers, damaged assets, adverse regulation, market-value declines, or a decision to abandon a business. Management may compare carrying value with recoverable amounts, expected cash flows, market evidence, or fair value, depending on the standard.

Business - This Explainer

Asset-Based Lending

Asset-based lending provides credit primarily against the value of eligible collateral, commonly accounts receivable and inventory. Availability changes through a borrowing-base formula rather than remaining a fixed percentage of the original commitment. The structure is used by manufacturers, distributors, retailers, and other companies with substantial working-capital assets. The lender applies advance rates and excludes ineligible items such as overdue, disputed, concentrated, foreign, or slow-moving assets. Reserves can reduce availability for taxes, dilution, returns, rent, or other risks. Borrowers submit periodic certificates, while field exams and appraisals test records and collateral quality.