

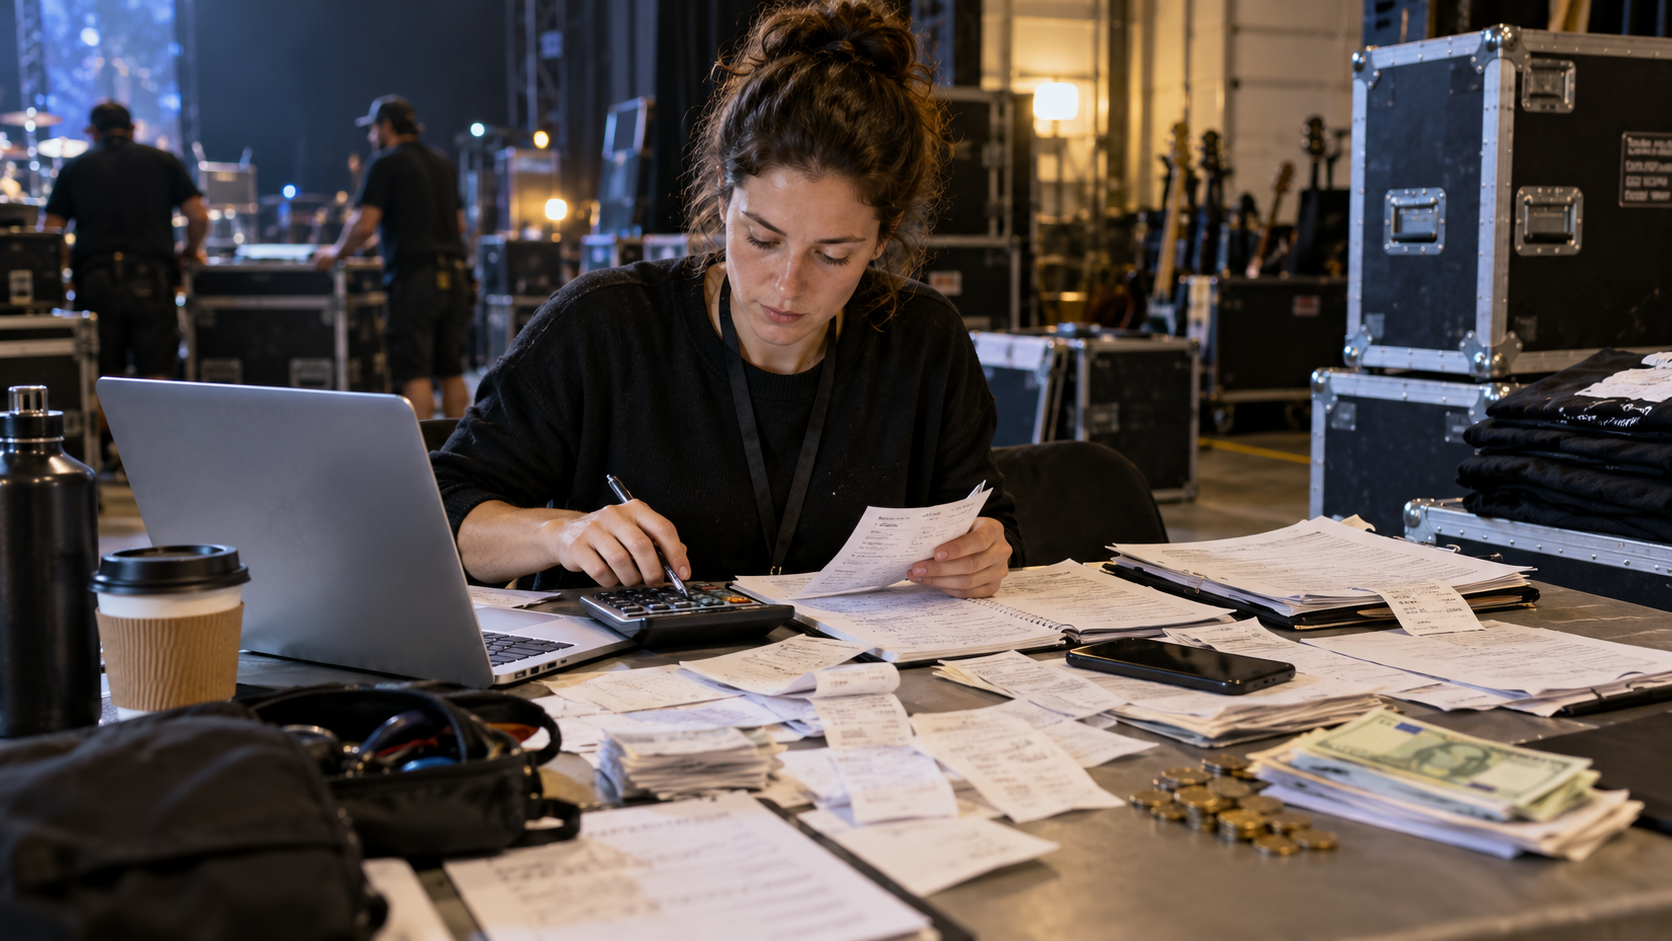
Tour Accounting Explainer
Tour Accounting describes a specific part of the entertainment workflow, but the visible result can hide the system behind it. Tour accounting is the financial administration of a traveling live production. It tracks budgets, show income, promoter settlements, payroll, per diems, travel, freight, vendors, merchandise, taxes, currencies, petty cash, credit cards, insurance, and reporting across many dates and jurisdictions. Looking first at the function rather than a famous example makes it easier to see what the term includes and what belongs to a neighboring role or process.
In practice, the work proceeds through a sequence of information, decisions, checks, and handoffs. Accountants build codes and forecasts, collect contracts and deal terms, process advances and payments, review daily expenses, reconcile cash and cards, prepare or audit show settlements, track variances, manage approvals, convert currencies consistently, and close the tour with supporting documents. The exact tools may change, but a dependable workflow always makes the current instruction, responsible person, and approved result clear enough for someone else to verify.
Responsibility is distributed rather than concentrated in a single job title. Artists, business managers, tour and production managers, agents, promoters, venue accountants, merch teams, crew, payroll providers, vendors, travel coordinators, tax advisers, insurers, auditors, and artist representatives supply or use the records. This network matters because entertainment projects combine creative judgment with contracts, technology, labor, safety, money, and deadlines, and no one department can independently control all of those constraints.
The term also has important boundaries. A sold-out show does not reveal profit, and cash received at a venue is not automatically distributable income. Guarantees, percentages, local taxes, withholding, currencies, commissions, production costs, chargebacks, reserves, labor rules, and incomplete receipts change the result. Descriptions therefore need context: practices differ by country, company, budget, format, and date, and an informal custom should not be presented as though it were a law or a universal technical standard. The larger value becomes clear when the process works consistently. Timely tour accounts make creative and routing decisions financially visible while there is still time to respond. Strong controls protect people handling cash and give artists and partners a traceable explanation of each show’s contribution. A useful explainer follows the underlying records and decisions from the beginning of the workflow to the audience-facing result, while leaving room for different but legitimate implementations. A practical way to read or discuss Tour Accounting is to begin with the basic definition and then identify the choices made in a particular example. Tour accounting is the financial administration of a traveling live production. It tracks budgets, show income, promoter settlements, payroll, per diems, travel, freight, vendors, merchandise, taxes, currencies, petty cash, credit cards, insurance, and reporting across many dates and jurisdictions. Next, ask who sets the relevant rules, who performs the work, and which results follow from creative judgment, law, contracts, technology, budget, or production limits. Similar-looking examples can operate differently because their audience, market, format, timing, and agreements are different. A sold-out show does not reveal profit, and cash received at a venue is not automatically distributable income. Guarantees, percentages, local taxes, withholding, currencies, commissions, production costs, chargebacks, reserves, labor rules, and incomplete receipts change the result. It also helps to distinguish a formal industry category from an informal critical label or one organization's current practice. That separation keeps a memorable anecdote from becoming a false universal rule. Dates and territories matter: tools, distribution systems, audience behavior, and standard agreements change, while older examples can preserve assumptions that no longer apply everywhere. Because the concept sits inside a larger workflow, examine what comes before and after it, which records move between stages, and where responsibility changes hands. This broader view prevents one visible task from being mistaken for the entire system. When a claim sounds absolute, compare it with a second kind of source and look for the conditions under which the claim is true. Then trace the process from the visible result back through the less visible decisions, handoffs, and quality checks that produced it. A reliable explanation of Tour Accounting separates the formal process from one organization's habits, identifies who holds each decision, and checks current rules, contracts, technology, and territorial practice before drawing a universal conclusion. Finally, compare the example with a contrasting case and note which part of the definition still holds. This method keeps the explanation grounded, highlights the people and systems behind the outcome, and leaves room for reasonable disagreement about hybrid or borderline cases.
Tour accounting is the financial administration of a traveling live production. It tracks budgets, show income, promoter settlements, payroll, per diems, travel, freight, vendors, merchandise, taxes, currencies, petty cash, credit cards, insurance, and reporting across many dates and jurisdictions.
Accountants build codes and forecasts, collect contracts and deal terms, process advances and payments, review daily expenses, reconcile cash and cards, prepare or audit show settlements, track variances, manage approvals, convert currencies consistently, and close the tour with supporting documents.
Artists, business managers, tour and production managers, agents, promoters, venue accountants, merch teams, crew, payroll providers, vendors, travel coordinators, tax advisers, insurers, auditors, and artist representatives supply or use the records.
A sold-out show does not reveal profit, and cash received at a venue is not automatically distributable income. Guarantees, percentages, local taxes, withholding, currencies, commissions, production costs, chargebacks, reserves, labor rules, and incomplete receipts change the result.
Timely tour accounts make creative and routing decisions financially visible while there is still time to respond. Strong controls protect people handling cash and give artists and partners a traceable explanation of each show’s contribution.
A reliable explanation of Tour Accounting separates the formal process from one organization's habits, identifies who holds each decision, and checks current rules, contracts, technology, and territorial practice before drawing a universal conclusion.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.