

On This Day in Business: March 10, 2000
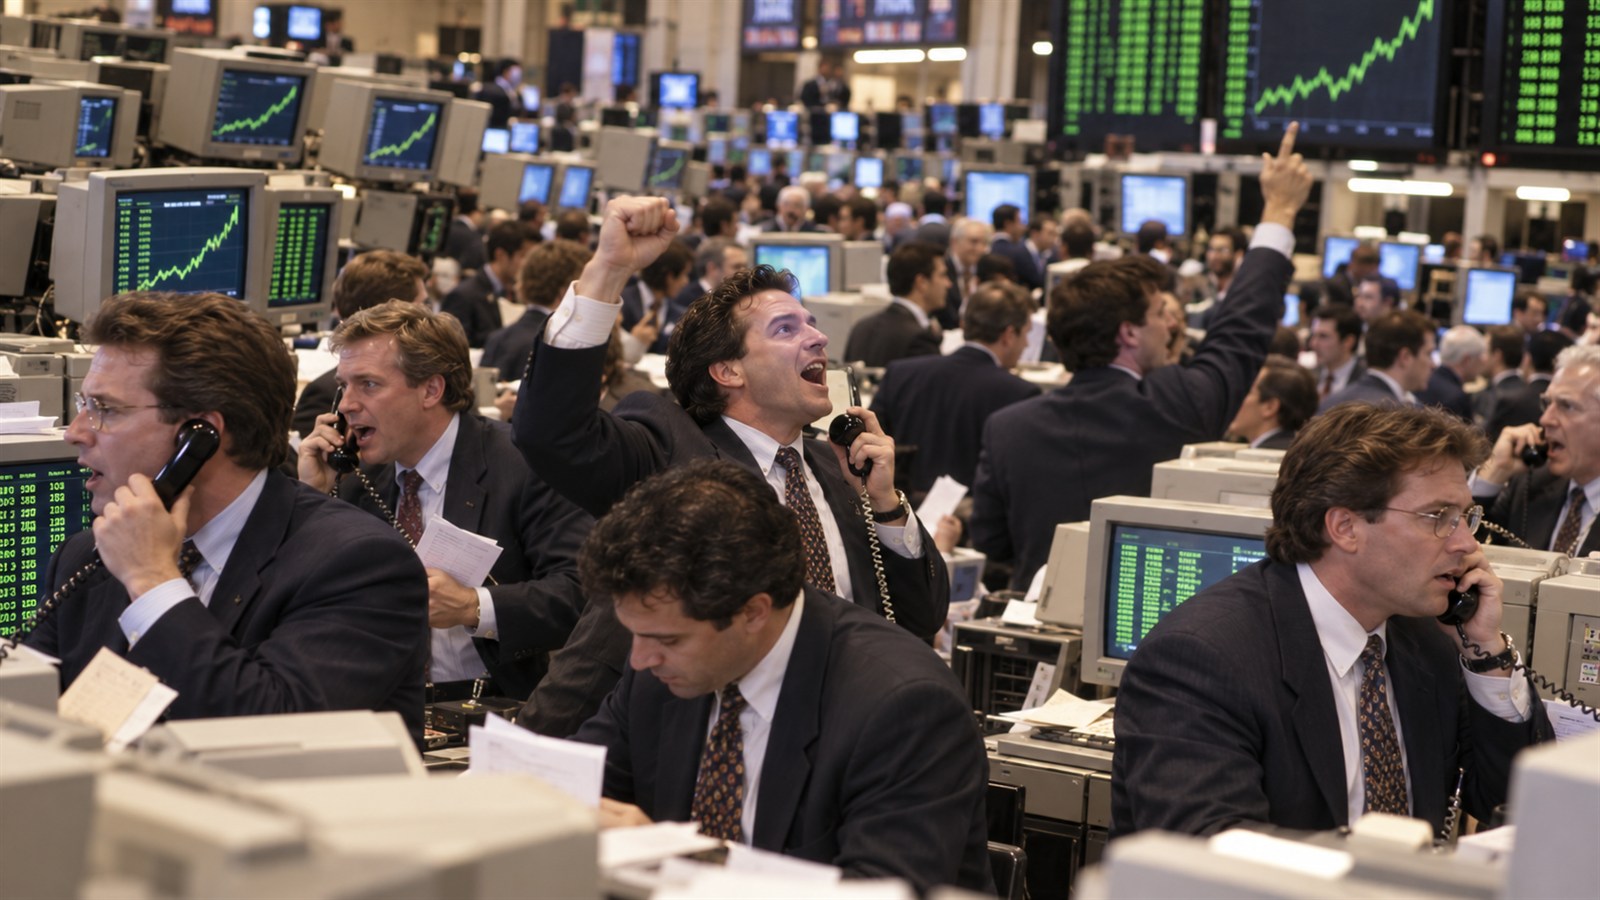
On March 10, 2000, the Nasdaq Composite closed at 5,048.62, the high point of the dot-com-era surge. Investors had poured money into technology and internet companies, persuaded that digital networks would remake commerce, media, and communication. Much of that conviction proved correct over the long term, but market prices often ran far ahead of earnings, cash flow, and sustainable business models. Startups could raise large sums on traffic growth, brand awareness, or the promise of scale, and rising shares appeared to validate still more investment.
The boom changed entrepreneurial behavior. Venture capital expanded, skilled workers accepted options in place of higher cash pay, and companies spent heavily to acquire customers before competitors. Public offerings gave young firms access to capital once reserved for more mature businesses. Suppliers, advertisers, landlords, and recruiters all benefited from the rush. Yet low financing discipline encouraged duplication and weak unit economics. When growth assumptions were questioned, many companies lacked profits or reserves that could support them through a change in investor sentiment.
After the March peak, the Nasdaq fell sharply and the decline continued for roughly two years. Numerous dot-com firms failed, technology investment slowed, and employees and investors absorbed large losses. Established companies also saw valuations contract. The crash did not erase the internet; it separated the durable infrastructure and services from many fragile financing stories. Surviving businesses gained talent, customers, or assets at lower costs, while investors rediscovered the importance of balance sheets, revenue quality, and the price paid for future growth.
The 2000 peak is a warning against confusing a transformative technology with any particular valuation. Markets can correctly identify a powerful trend while mispricing the timing, winners, and profits it will produce. Network effects and rapid adoption can support exceptional companies, but they do not suspend competition or the need for cash. For business leaders, the episode also shows how plentiful capital affects strategy: it can fund genuine innovation while rewarding speed without resilience. March 10 remains a useful marker of optimism reaching the point where expectations became harder for operating results to sustain. The aftermath also changed how boards and employees viewed equity compensation. Options that appeared to provide effortless upside could lose value quickly, while concentrated company stock exposed workers to losing savings and employment together. Better risk disclosure could not remove that correlation. The boom and decline therefore affected corporate finance inside the firm as well as public portfolios, reminding leaders that incentives tied to market price can encourage commitment but also magnify short-term expectations and personal vulnerability.
Internet adoption, falling technology costs, venture funding, and enthusiasm for network businesses drove extraordinary demand for technology shares.
Many young companies prioritized rapid customer growth and market presence while investors accepted limited profits or untested economics.
The Nasdaq Composite closed at 5,048.62 on March 10, 2000, its highest dot-com-era finish.
Once confidence weakened, companies dependent on continued financing faced severe pressure, and the technology-heavy index entered a deep decline.
The correction destroyed substantial wealth and many firms, but internet infrastructure and genuinely useful digital business models continued developing.
The peak remains a lesson that technological importance does not guarantee every participant's survival or justify every price paid for growth.
Explore more of "On This Day ..."
Discover more events from the same date across news, politics, technology, sports, and other fields. Each link highlights significant moments that shaped history on different fronts.