

Film Tax Incentives Explainer
Film tax incentives are government programs designed to attract or retain screen production by reducing some qualifying costs. Depending on the jurisdiction, the benefit may be a refundable or transferable tax credit, a rebate, a grant, or a deduction. A headline percentage is only the beginning. Programs define eligible project types, minimum spending, resident and nonresident labor treatment, geographic requirements, compensation caps, application windows, funding limits, and whether the incentive is awarded before or after production.
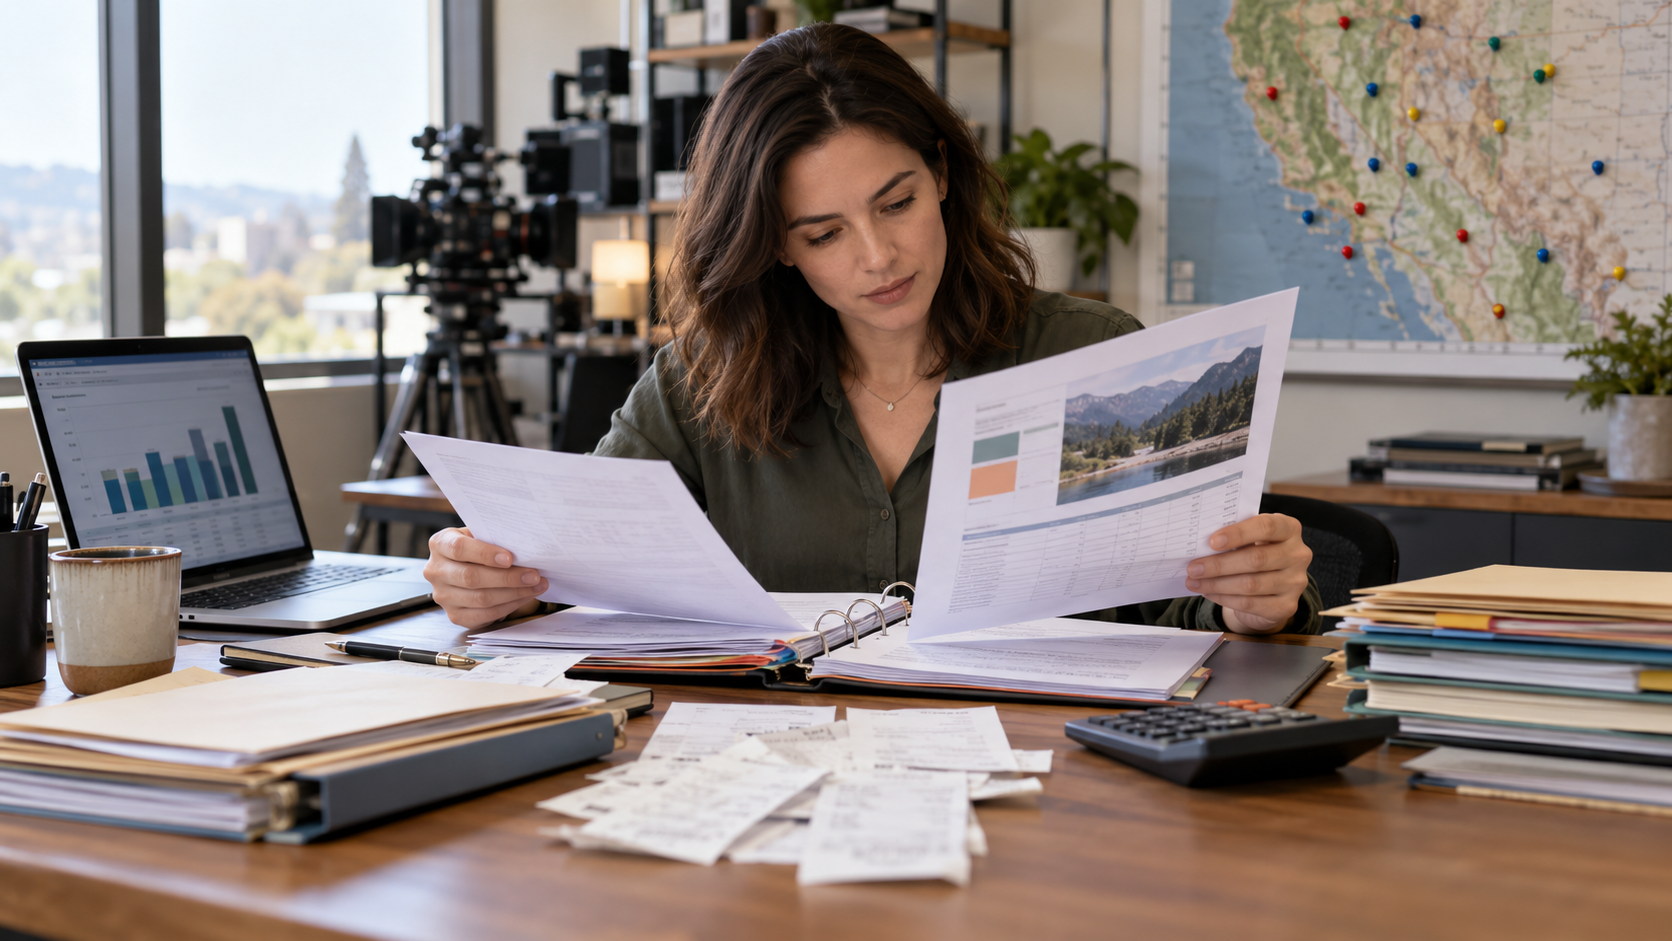
Productions usually apply for preliminary approval, track qualifying expenses in separate accounts, follow required reporting rules, and submit final cost documentation. Payroll records, vendor addresses, invoices, proof of payment, insurance, and tax compliance can determine eligibility. Some programs reward local hiring, rural locations, post-production, permanent facilities, or an on-screen acknowledgment. An expense can be necessary to the film yet fail to qualify because it was incurred outside the territory, paid to an ineligible party, or documented incorrectly.
The credit often arrives after work and audit are complete, while crews and vendors must be paid during production. Producers may therefore borrow against the expected benefit or sell a transferable credit to another taxpayer. Lenders and buyers discount for time, fees, uncertainty, and legal conditions, so a nominal credit does not equal cash of the same amount. The finance plan must also account for application costs, audits, interest, and the possibility that some spending will be disallowed.
Governments evaluate these programs through different measures: local employment, vendor activity, tourism exposure, infrastructure, workforce development, tax revenue, and the opportunity cost of public funds. Reported production spending is not the same as net economic benefit. Analysts may disagree about how much activity would have occurred without the incentive, how temporary jobs should be counted, or which public costs and displaced activities belong in the comparison. When reading an incentive announcement, ask which program applies, whether the amount is estimated or certified, what spending base produced it, and how the credit becomes cash. Also separate production location from story setting; a film may double one place for another because the financial and logistical package is favorable. Incentives can influence where work occurs, but scripts, stages, crews, weather, exchange rates, and creative needs remain part of the decision. A practical way to read or discuss Film Tax Incentives is to begin with the basic definition and then identify the choices made in a particular example. Film incentives can take the form of refundable or transferable credits, rebates, grants, or deductions tied to defined activity. Next, ask who sets the relevant rules, who performs the work, and which results follow from creative judgment, law, contracts, technology, budget, or production limits. Similar-looking examples can operate differently because their audience, market, format, timing, and agreements are different. Because benefits often arrive after production, projects may borrow against them or sell transferable credits at a discount. It also helps to distinguish a formal industry category from an informal critical label or one organization's current practice. That separation keeps a memorable anecdote from becoming a false universal rule. Dates and territories matter: tools, distribution systems, audience behavior, and standard agreements change, while older examples can preserve assumptions that no longer apply everywhere. When a claim sounds absolute, compare it with a second kind of source and look for the conditions under which the claim is true. Then trace the process from the visible result back through the less visible decisions, handoffs, and quality checks that produced it. A meaningful incentive figure identifies the jurisdiction, qualifying base, certification stage, monetization costs, and conditions attached. Finally, compare the example with a contrasting case and note which part of the definition still holds. This method keeps the explanation grounded, highlights the people and systems behind the outcome, and leaves room for reasonable disagreement about hybrid or borderline cases.
Film incentives can take the form of refundable or transferable credits, rebates, grants, or deductions tied to defined activity.
Qualifying rules may cover project type, minimum spend, location, labor residency, vendor status, compensation caps, and application timing.
Detailed payroll and vendor records support final certification; a production expense is not automatically an eligible expense.
Because benefits often arrive after production, projects may borrow against them or sell transferable credits at a discount.
Program evaluation distinguishes gross spending from additional local activity, public cost, tax return, and long-term workforce effects.
A meaningful incentive figure identifies the jurisdiction, qualifying base, certification stage, monetization costs, and conditions attached.
Explore more "Explainers"
Discover additional explainers across politics, science, business, technology, and other fields. Each explainer breaks down a complex idea into clear, everyday language—helping you better understand how major concepts, systems, and debates shape the world around us.